Fraudio Data Led Insights
The data behind Early Fraud
Fraudio analysed a representative sample drawn from its wider transaction data, covering more than 127.5 million transactions processed between January 2025 and April 2026, following 3,923 merchants from their very first recorded payment.
The question was simple: how soon does fraud find a new business? The answer is sooner than most risk teams expect.
Fraud tends to arrive when a merchant has the least history to judge it against, and when it does, it rarely looks out of place. Here is how the first 90 days break down.
The first 90 days in numbers
Problem with
Early Fraud
- Every new merchant is a blind spot. Fraud can strike long before you know what normal looks like.
- The risk isn't just earlier, it's heavier. The fraud rate per transaction was 2.9 times higher during merchants' first 90 days.
- Fraud strikes when there is the least data to catch it. Nearly half of new merchants hit by fraud in their first 90 days saw it within their first 30 days, and one in five within their first week. That is long before any meaningful baseline of normal customer behaviour exists, so rules and models that rely on a merchant's own history are effectively running blind.
- Without context from day one, payment companies are left learning what fraud looks like the expensive way: by absorbing the losses first.
Main bottlenecks
The situation
before Fraudio
Merchant acquirers and Issuers previously relied on the traditional approach of a rules-based engine for each transaction. Those rules were hard-coded rules with an “if-then” framework that resulted in many false positives and created disruption in the business of their customers. This system required a large team of people to check every alert, hence why they needed an AI-assisted system to handle the workload.
- Risk of large losses from early fraud
- Time-consuming and unscalable investigations’ workflow/process, with too many false positives
- Existing alerts only notify when loss exposures are significant
- Growth ambitions capped by limitations on scaling the fraud & risk team
What is the Solution?
Reduce false positives and false negatives
Efficiently monitor fraud in real-time
Enabling further efficiency within the existing fraud investigation teams
Significantly Reduce fraud losses
The Payment Fraud Detection (PFD)
Product
Developed to support companies growth, this product provides fraud investigation teams timely information about the risk of early fraud on merchants, with Fraudio continuously monitoring all money flows, conducting peer group analyses, behavioural pattern analysis, and transaction sequence analysis.
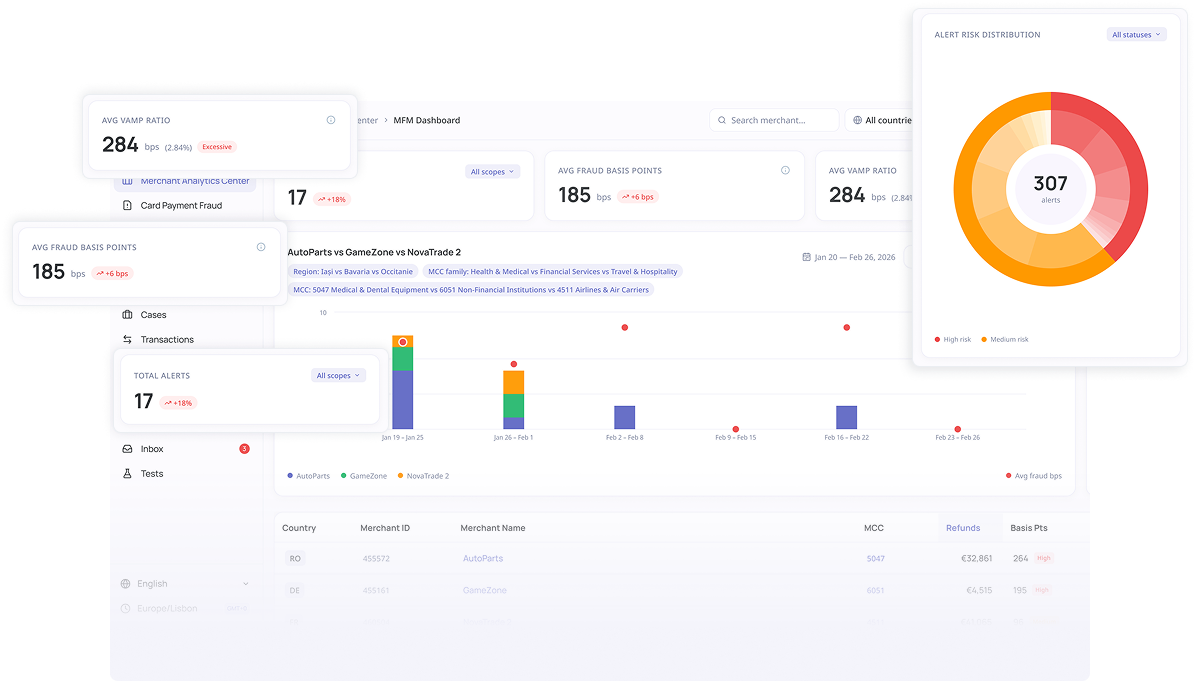
After implementing Fraudio’s PFD product, Merchant Acquirers and Issuers have seen the following positive results:
- False positives (alerts indicating fraud has occurred that end up being incorrect) have decreased dramatically.
- When fraudulent activity is detected, Fraudio informs immediately, so that emergency measures can be implemented to stop financial losses.
- Efficiency of the transactional behaviour monitoring has increased due to the real-time monitoring.
Main benefits
Payment Fraud Detection Product
Real-time fraud scoring powered by AI trained on billions of networked transactions. Every payment gets a clear Green, Yellow or Red decision in milliseconds, and integration takes days.- Quicker time to receive early fraud alerts significantly reduce losses
- Unlocking the ability to scale your business faster without scaling your team
- Enabling hyper efficiency from existing fraud investigations teams, allowing them to focus on high-value investigations
Advantages over other anti-fraud solution vendors
“Fraudio was able to adapt to us, and not us adapting to them. Most of the tools in the market right now have a “one size fits all” solution that is rigid and very demanding. Fraudio worked with us through various workshops to learn our needs and adapt their way of operations to our model. After giving them some data, they were able to transform their engine to adhere to our models to give us valuable results with a time to market and time to release that was much, much shorter compared to other systems.”
Giorgios Gkionis
Chief Software Architect (Risk and AML) at Viva Wallet
“The key difference between us and our competitors is that we don’t produce custom models per client, we produce our own centralised models by translating our clients' data schemas to our internal one. This allows us to give clients access to the world class fraud detection models that we have been producing over the years as soon as they're integrated.”
João Moura
CEO of Fraudio